Tag: Pharma

  • Ultragenyx Rare Disease Voucher Sales Secure $413M for More Potential Pipeline Building

    Ultragenyx Rare Disease Voucher Sales Secure $413M for More Potential Pipeline Building

    Ultragenyx recently received two separate FDA approvals for gene therapies in the span of a month, each regulatory nod accompanied by a voucher the company could use to speed up the future review of another rare disease drug. In the past week, Ultragenyx has reached separate deals to sell each regulatory fast pass.

    The Novato, California-based biotech announced Wednesday a definitive agreement to sell a voucher for $203 million, following a deal last week to sell a voucher for $210 million. The identities of both voucher buyers were undisclosed and the purchases still need to meet closing conditions. But the deals put Ultragenyx in line for non-dilutive capital that the rare disease specialist can use to bolster its drug pipeline.

    Congress created the voucher program to incentivize drug development in rare diseases. Companies awarded a regulatory approval in a rare pediatric disease can receive one of these vouchers, which cuts the standard review time of 10 months down to six. These vouchers may be sold, and many voucher recipients opt to sell them to big pharmaceutical companies. Demand for these regulatory fast passes has pushed prices higher; most of the vouchers sold this year fetched prices of $200 million or more.

    Ultragenyx received a voucher alongside the late August approval of Gengylcos, a gene therapy for a rare inherited enzyme deficiency called glycogen storage disease type Ia. Another voucher came from the mid-September FDA nod for Fayuvi, a gene therapy for a different rare inherited enzyme deficiency called Sanfilippo syndrome Type A. Each product is the first approved therapy for its respective ultra-rare indication.

    While the Ultragenyx gene therapies carry multi-million-dollar price tags, neither product is expected to become a big revenue driver. Much of the company’s future financial expectations had rested on apazunersen, which was in development for Angelman syndrome, a rare genetic neurological disorder with no FDA-approved therapies. Last month, Ultragenyx reported this antisense oligonucleotide drug failed its Phase 3 test. The company said the disappointing trial outcome would lead to a corporate restructuring and expense reductions.

    The Angelman drug came from an acquisition. Ultragenyx’s two gene therapies also came from business deals. The capital from the voucher sales could be applied toward another deal for a different rare disease therapeutic candidate. While the company made clear its intent to sell both vouchers, it has not said how it will use the proceeds. As of the end of June, Ultragenyx reported its cash position was $436 million. The company is expected to report third quarter 2026 financial results in November.

    Ultragenyx previously received vouchers for rare disease drug approvals in 2017 and 2018. In a prepared statement, Chief Financial Officer Howard Horn noted that the Sanfilippo gene therapy benefited from capital generated by a previous voucher sale, “demonstrating the important role the [priority review voucher] program plays in helping companies develop transformative therapies for rare disease patients.”

    In a Wednesday research note, William Blair analyst Lachlan Hanbury-Brown said that even though Ultragenyx is launching two new gene therapies, the company’s pipeline lacks any clinical catalysts to drive value for the company’s stock in the next year. But the sale of the two vouchers significantly bolsters the biotech’s balance sheet with non-dilutive capital.

    “We look forward to hearing how management plans to strategically deploy this additional capital, as well as details on the company’s expense reductions plans, which we believe will help achieve [generally accepted accounting principles] profitability in 2027,” Hanbury-Brown said.

    Photo: CaptureTheWorld, Getty Images
  • STAT+: FDA adcomm members’ ties to industry under scrutiny

    STAT+: FDA adcomm members’ ties to industry under scrutiny

    Elaine’s stories explore the boom in new obesity treatments, new drug payment models, the ways companies are affected by FDA changes, and the emerging psychedelics drug sector. She co-writes The Readout newsletter, and co-hosts STAT’s weekly biotech podcast, The Readout Loud. You can reach Elaine on Signal at elaineywchen.70.

    Good morning. Yesterday, we got the devastating news that STAT’s infectious disease correspondent, Helen Branswell, passed away. She was a reporter I always looked up to and was also an incredibly generous colleague. Please take the time to read this tribute to her.

    The need-to-know this morning

    • Liquidia and United Therapeutics reached a settlement agreement that resolves their ongoing patent litigation over Liquidia’s treatment for pulmonary arterial hypertension. 

    Researchers in Pittsburgh are launching a novel type of GLP-1 trial — testing not only if the drug will help people with addiction, but also if it will help reduce recidivism while improving other employment, health, and housing outcomes.

    The Center for Addiction Science, Policy and Research (CASPR), a non-profit organizing the effort, and the Allegheny County Department of Human Services are planning to launch the trial in early 2027. They will enroll up to 1,200 adults with alcohol use disorder, opioid use disorder, or both, who are also at high risk of criminal-justice involvement. Half will be randomly assigned to take Novo Nordisk’s Wegovy, according to a press release issued yesterday.

    STAT+ Exclusive Story

    Already have an account? Log in

    STAT+

    STAT+

    This article is exclusive to STAT+ subscribers

    Unlock this article — plus in-depth analysis, newsletters, premium events, and news alerts.

    Already have an account? Log in

    View All Plans

    To read the rest of this story subscribe to STAT+.

    Subscribe

  • STAT+: Pharmalittle: We’re reading about Sanofi settling an EU antitrust probe, ‘pharma bro’ Shkreli, and more

    STAT+: Pharmalittle: We’re reading about Sanofi settling an EU antitrust probe, ‘pharma bro’ Shkreli, and more

    By Ed Silverman

    Oct. 14, 2026

    Pharmalot Columnist, Senior Writer

    Good morning, everyone, and welcome to the middle of the week. Congratulations on making it this far, and remember there are only a few more days until the weekend arrives. So keep plugging away. After all, what are the alternatives? While you ponder the possibilities, we invite you to join us for a needed cup of stimulation, which we hope to find shortly since we are on the road. Perhaps we can meet? Meanwhile, here is the latest menu of tidbits to help you on your way. We hope you conquer the world and have a wonderful day. And as always, please do stay in touch. We appreciate feedback, tips, and criticism. …

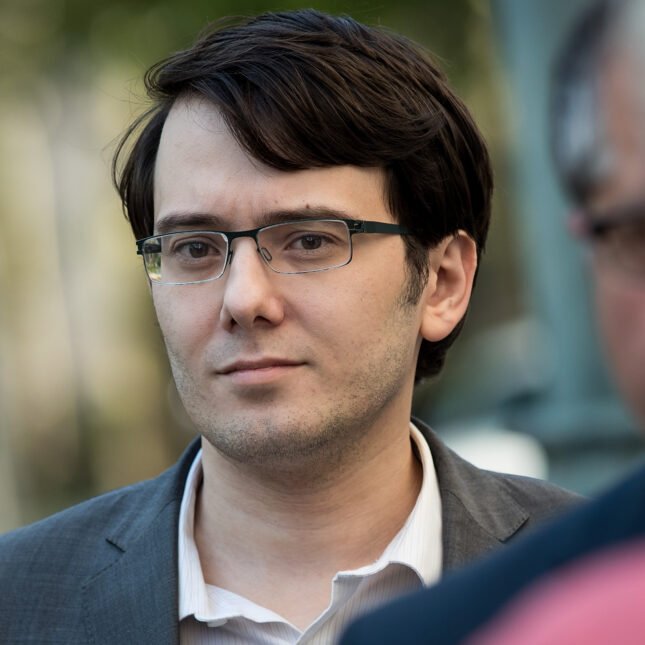
    Martin Shkreli is back, but the U.S. Federal Trade Commission is not happy, STAT says. The agency and seven states asked a U.S. court to hold Shkreli in contempt for “flagrantly and repeatedly” violating a court order banning him from working in the pharmaceutical industry. Shkreli, known as “pharma bro” for imperiously defending his decision to raise the price of a drug by 5,000%, was sentenced to seven years in prison for defrauding investors in 2018. Before his release in 2022, a court banned him from ever working in the industry again, saying he illegally tried to prevent generic competition to the drug. Since then, he became a prolific trader in pharma stocks, broadcasting his analysis in posts and livestreams on X and other platforms.

    European Union antitrust regulators accepted concessions from Sanofi to settle an investigation into an allegedly “misleading” campaign that disparaged the only rival flu vaccine recommended for vulnerable patients at risk for developing the illness, STAT tells us. In doing so, the company avoided being fined. The European Commission had suggested that Sanofi portrayed the Fluad vaccine marketed by CSL Seqirus as inferior to its own Efluelda vaccine in a communication campaign that primarily targeted health care professionals in Germany and France. Sanofi holds a dominant position in both countries, according to the EC.

    STAT+ Exclusive Story

    Already have an account? Log in

    STAT+

    STAT+

    This article is exclusive to STAT+ subscribers

    Unlock this article — plus in-depth analysis, newsletters, premium events, and news alerts.

    Already have an account? Log in

    View All Plans

    To read the rest of this story subscribe to STAT+.

    Subscribe

  • Roche Puts Up $100M to Pursue Promising But Competitive New Target in Obesity

    Roche Puts Up $100M to Pursue Promising But Competitive New Target in Obesity

    For Roche to catch up to Eli Lilly and Novo in metabolic medicines, it needs its drugs to offer differentiation from those rivals. Roche might have just found a way, agreeing to pay $100 million to license a contender that brings a different modality to a new obesity target.

    The drug comes from Shanghai-based Rona Therapeutics. According to deal terms announced Tuesday, Roche gains global rights to the molecule, whose name was not disclosed. It’s the latest in a series of Roche business deals to build up the company’s metabolic drug pipeline.

    Formed in 2021, Rona develops RNA interference (RNAi) drugs, an approach that uses small interfering RNA (siRNA) to degrade messenger RNA, interfering with the translation of a disease-driving protein. This approach is sometimes called “gene silencing.” RNAi drugs first reached patients as treatments for liver disorders, but the field has been working to expand the modality beyond the liver. Roche’s new drug comes from a Rona platform technology that enables extrahepatic drug delivery. Rona also claims its therapies offer the potential to be best in class with longer duration, deep knockdown of target proteins, and improved tolerability.

    The Rona pipeline lists two obesity drug, both in preclinical development for undisclosed targets. The target of Roche’s newly licensed drug is activin receptor-like kinase 7 (ALK7), a protein that is primarily expressed in fat cells. ALK7 plays a role in a signaling pathway that regulates fat storage, the breakdown of stored fats, and the balance of the intake and expenditure of energy.

    Rona points to genetic studies showing that reducing ALK7 activity is associated with favorable results in fat distribution and metabolic measures. Unlike the currently available peptide drugs designed to mimic gut hormones to affect appetite and energy intake, Ronas say ALK7 inhibition acts directly on the biology of fat tissue. This different approach offers the potential for use as a standalone treatment or in combination with established obesity drugs.

    “Obesity represents a significant health challenge that requires differentiated treatment options for patients,” Boris Zaïtra, Roche head of corporate business development, said in a prepared statement. “We are excited to partner with Rona Therapeutics, complementing our robust [cardiovascular, renal & metabolic disease] pipeline and reinforcing our commitment to delivering next-generation metabolic therapies.”

    Roche jumped into obesity drug R&D with the $2.7 billion acquisition of Carmot Therapeutics in 2024. The Carmot drugs address GLP-1 and GIP receptors, the same targets as Lilly and Novo’s obesity drugs. Last year, Roche began a partnership on petrelintide, a Zealand Pharma peptide designed to activate the receptor for amylin, a hormone key to regulating blood sugar and appetite. One goal for petrelintide is reducing fat in a way that does not also lead to muscle loss, a known problem for obesity drugs. Roche added yet another approach to obesity in August, licensing a Hanmi Pharmaceutical peptide designed to activate CRF2 receptors to reduce fat and increase muscle mass.

    With the Rona drug, Roche joins a growing group of companies testing siRNA therapies in obesity. Wave Life Sciences’ siRNA drug WVE-007 goes after a different but related target. It’s designed to silence INHBE, the gene that provides the instructions for activin E, a liver-secreted protein that activates ALK7. Wave has said WVE-007 is intended to stimulate the breakdown of fat while preserving muscle. Late last year, Wave announced preliminary Phase 1 results that it said support once- or twice-yearly dosing. Last month, the company began a Phase 2a study testing WVE-007 in combination with the Lilly obesity drug Zepbound.

    GSK joined the ALK7 chase in May, licensing rights to Suzhou Siran Biotechnology’s SA030, a long-acting siRNA in development for metabolic and vascular diseases. The deal calls for SiranBio to complete the ongoing Phase 1 study. After that, GSK will be responsible for further development of the drug outside of Greater China.

    Arrowhead Pharmaceuticals has two siRNA therapies in development for obesity: the ALK7-targeting drug ARO-ALK7 and the INHBE gene-silencing therapy ARO-INHBE. Both are in Phase 1/2a testing. Meanwhile, RNAi therapies pioneer Alnylam Pharmaceuticals has an INHBE-targeting siRNA drug in preclinical development for obesity.

    Biotech company iBio takes yet another approach with IBIO-610, an antibody designed to block activin E. In July, iBio reported results in monkey tests showing a single dose achieved near complete inhibition of the target protein through eight weeks. These results also showed fat loss and muscle preservation.

    The $100 million that Roche agreed to pay Rona consists of an upfront and near-term milestone payments. Rona could receive up to $1.06 billion more if the drug achieves milestones, plus royalties from sales if it reaches the market.

    Photo: Giuseppe Aresu/Bloomberg, via Getty Images

  • STAT+: FTC demands Martin Shkreli divest his pharma stocks

    STAT+: FTC demands Martin Shkreli divest his pharma stocks

    Federal agency and seven states accuse ‘pharma bro’ of ‘flagrantly’ violating a court order

    Martin ShkreliDrew Angerer/Getty Images

    By Jason Mast

    Oct. 13, 2026

    General Assignment Reporter

    Jason is a general assignment reporter, with particular focus on genetic medicine and rare disease. Confidential tips can be sent on Signal at JasonMast.77.

    Martin Shkreli is back. The Federal Trade Commission isn’t happy. 

    The FTC and seven states on Tuesday asked a federal court to hold Shkreli in contempt for “flagrantly and repeatedly” violating a court order banning him from working in the pharmaceutical industry. 

    Shkreli, who became known nationwide as “pharma bro” in the 2010s for imperiously defending his decision to raise the price of an anti-parasitic drug called daraprim by 5,000%, was sentenced to seven years in prison for defrauding investors in 2018. Before he was released in 2022, a court banned him from ever working in the drug industry again, saying he illegally tried to prevent generic competition to daraprim.

    STAT+ Exclusive Story

    Already have an account? Log in

    STAT+

    STAT+

    This article is exclusive to STAT+ subscribers

    Unlock this article — plus daily coverage and analysis of the pharma industry — by subscribing to STAT+.

    Already have an account? Log in

    View All Plans

    To read the rest of this story subscribe to STAT+.

    Subscribe

    1. General Assignment Reporter

      Jason is a general assignment reporter, with particular focus on genetic medicine and rare disease. Confidential tips can be sent on Signal at JasonMast.77.

  • STAT+: Pharmalittle: We’re reading about concerns over a rare disease drug, pharma payments to docs, and more

    STAT+: Pharmalittle: We’re reading about concerns over a rare disease drug, pharma payments to docs, and more

    By Ed Silverman

    Oct. 13, 2026

    Pharmalot Columnist, Senior Writer

    Rise and shine, everyone, another busy day is on the way. And it is getting off to a pleasant start here on the Pharmalot campus, where clear blue skies and comfy breezes are greeting us. As for the official mascots, they are happily snoozing in their respective corners. As for us, we are firing up the trusty kettle for another cup of stimulation. Our choice today is butter pecan. Of course, you are invited to join us. For the full experience, we are now hawking replicas — take a look. Meanwhile, here are a few items of interest. As always, do keep in touch. We appreciate feedback, criticism, and tips. …

    Two months after the release of an open letter on potential safety issues tied to a rare disease drug sold by Neurocrine Biosciences, patient advocates and some experts are expressing growing alarm over the perceived risks of the therapy, STAT reports. The drug, approved to treat Prader-Willi syndrome, which can cause an insatiable feeling of hunger, has been linked to the deaths of seven people and the  hospitalization of nearly 100 others — all since the treatment, called Vykat XR, was approved 18 months ago. Case reports on those deaths and hospitalizations that were submitted to regulators do not prove causality; many of the Vykat cases involved complex medical issues and multiple medications. But some experts say the evidence is sufficient to conclude Vykat is causing unacceptable harm.

    The gifts and payments that doctors receive from drugmakers increased inappropriate prescribing and the number of prescriptions written, likely leading to rising health care costs, STAT writes, citing a Cochrane review of dozens of previous studies that have explored the influence the pharmaceutical industry has on medical practice. In addition, pharmaceutical advertising or education aimed at doctors may also increase inappropriate prescribing, probably increases the number of prescriptions written, and may increase the costs of prescriptions. But conflict-of-interest policies that restrict or manage interactions between companies and doctors probably improved prescribing practices.

    STAT+ Exclusive Story

    Already have an account? Log in

    STAT+

    STAT+

    This article is exclusive to STAT+ subscribers

    Unlock this article — plus in-depth analysis, newsletters, premium events, and news alerts.

    Already have an account? Log in

    View All Plans

    To read the rest of this story subscribe to STAT+.

    Subscribe

  • What Corporate Venture Funds Get Wrong about Strategic Value

    What Corporate Venture Funds Get Wrong about Strategic Value

    A venture fund’s objective is to invest capital into early-stage companies to fuel growth, increasing the probability that they are acquired or reach public markets. That’s how an “exit” is achieved, with the invested capital returned at a risk-adjusted profit. Corporate venture capital (CVC) differs from orthodox venture capital because, alongside financial returns, a CVC’s goal is often to create strategic value for a core business.

    Delivering this strategic value is much easier said than done, and therefore not well addressed by most CVC funds. 

    Outlined below are four distinct practices that optimize strategic and financial value. 

    Define strategic value alongside financial return

    Strategic value comes in many forms. Pharma corporate venture should develop investments that might generate a valuable new target, drug, or vaccine candidate, improve the probability of pipeline success, reduce the cost of R&D, accelerate clinical trials — and more through the entire value chain. It is not necessary to acquire such businesses outright, but it is necessary to cultivate them into standardized, scaled solutions for scientists, regulators, clinicians, patients, and payors.

    Assessing the value of an asset — financial and/or strategic — is as much art as science. Financial value can be estimated using discounted cash flow analysis, which relies on pro forma projections and assumptions about future market pricing and multiples, or through comparable-company analysis. Quantifying strategic value is much more difficult. One derivative indicator of strategic value is whether the core CVC business engages with the portfolio company, through piloting, partnering, licensing, and/or purchasing products or services. A CVC that can’t generate this type of engagement is just delivering capital without a strategic return. 

    Lead internal collaborations that power sourcing and diligence

    Placing relevant strategic investments requires deep familiarity with the parent company’s objectives and priorities. This means dedicated internal workstreams with business leaders and subject matter experts who help refine and prioritize use cases and understand unmet needs. In-house CVC resources also help with pipeline building and technical, scientific, and clinical due diligence. Proper engagement is time-consuming and requires operational, process, and communication excellence — skills anathema to the normal concerns of most venture investors.

    Many benefits accrue from generating that upfront buy-in. Deep collaboration raises the CVC’s probability of succeeding in highly scientific and technical markets. It also instills early business awareness and engagement, so portfolio companies develop faster pilots and larger partnerships, executable in a shorter timeframe.

    Drive leverage through syndication

    Most CVC investors are equipped to lead negotiations and price rounds, but there’s a strong case for prioritizing syndicate creation. 

    Syndication provides leverage through agile, coordinated activity on negotiating terms, dividing or delegating board activities, and considering future mergers and acquisitions. It also extends financial leverage, allowing a fund to cover more of the market and back a broader range of strategic interest areas. Joining syndicated deals priced by expert financial investors tends to produce a fair market price. A CVC can always walk away when pricing runs ahead of what its internal modeling supports. 

    Even with reduced board involvement, a fund can stay engaged through shareholder and information rights — quarterly financials, board materials, regular check-ins — whether it holds a board or observer seat or is simply an shareholder. 

    Occasionally, a CVC will need to play a more significant company-building role, In such cases it can place a convertible note or lead a round outright — but always with an eye toward delegating responsibility over time. The correct level of involvement is a case-by-case decision, considering the strategic relevance of the platform, the stage of the company, and the experience of its board and management team.

    Deliver the payoff 

    None of this works as one single move, but as a pattern: sourcing shaped by internal collaboration, pricing and development sharpened by syndication, and continued engagement all the way to exit. Funds that operate this way tend to see their strategic and financial returns reinforce each other over time rather than trade off against one another.

    The key lies in recruiting and training leaders who roll up their sleeves and work seamlessly with internal partners. When portfolio investments help a business develop better therapies or reach patients faster, they deliver strategic value — and ultimately value to patients and providers.

    Photo: Hong Li, Getty Images

    David M. Rubin

    David M. Rubin, Ph.D., is a Managing Director in Merck GHIF, where he leads the drug discovery and precision medicine practice. Dr. Rubin ran and helped build life sciences companies in the USA, UK, Denmark, Hungary, and India. He was awarded National Institutes of Health and American Cancer Society Fellowships to support his research at Harvard Medical School on ubiquitin-dependent protein degradation. He received a B.A. in biology from SUNY Binghamton and a Ph.D. from Temple University. Junk Birds, his collection of previously published short stories, was published in 2025.

    This post appears through the MedCity Influencers program. Anyone can publish their perspective on business and innovation in healthcare on MedCity News through MedCity Influencers. Click here to find out how.

  • Asahi Kasei Acquisition Pays Off With FDA Approval for Novel Herpes Drug

    Asahi Kasei Acquisition Pays Off With FDA Approval for Novel Herpes Drug

    Patients with lesions caused by herpes simplex virus have a new FDA-approved treatment option, an oral antiviral drug from Asahi Kasei.

    The late Friday regulatory decision covers the treatment of adults whose lesions do not respond to the three oral antivirals that make up the current standard of case. Asahi Kasei’s once-daily pill, known in development as pritelivir, will be commercialized under the brand name Hovilpri.

    In people with healthy immune systems, herpes simplex virus (HSV) infection is often asymptomatic or causes mild disease. But in people with weakened immune symptoms — those who have undergone a transplant procedure, or patients with HIV, cancer, or autoimmune disorders — HSV infection can occur more frequently and with greater severity. While oral antivirals are available to treat HSV, viral mutations can lead to resistance to these older drugs. There are alternative treatment options, but they require intravenous dosing.

    Hovilpri gives patients the choice of an oral drug with a different mechanism of action. This small molecule is designed to inhibit a complex of enzymes key to the synthesis of viral DNA. The drug was developed to treat both types of HSV, HSV-1 and HSV-2.

    The regulatory submission for Hovilpri was based on the results of a Phase 3 study that showed statistically significant superiority in lesion healing up to day 28 compared to the physician’s choice of treatment. The most common adverse reaction reported for the study drug was headache.

    “Today’s approval delivers the first FDA-approved treatment for refractory mucocutaneous HSV lesions with a novel mechanism of action in nearly 30 years and marks an important advancement for immunocompromised adults,” Stacy Wheeler, CEO of Asahi Kasei Therapeutics in the U.S. and Europe, said in a prepared statement. “Hovilpri offers a new oral treatment option for adult patients with a persistent, difficult-to-treat disease.”

    Hovilpri was originally developed by AiCuris Anti-Infective Cures, a Germany-based biopharmaceutical company acquired by Asahi Kasei for €780 million (about $919 million). In the February acquisition announcement, Tokyo-based Asahi Kasei said the deal strengthens the company’s presence in severe infectious disease. It added that HSV patients addressed by Hovilpri are commonly seen in transplant centers and specialized hospital settings where the company has established commercial relationships and infrastructure.

    Asahi Kasei has been expanding its portfolio and pipeline via business deals. In 2020, the company closed the 8.3 billion Danish krone (about $1.3 billion) acquisition of Veloxis Pharmaceuticals, a company that develops and sells therapies for organ transplant patients. The Japanese company’s 11.8 billion Swedish krona (about $1.18 billion) acquisition of Calliditas Pharmaceuticals in 2024 brought a portfolio that includes Tarpeyo, which has FDA approval for treating the rare kidney disorder immunoglobulin A nephropathy.

    The Aicuris acquisition brought more than Hovilpri. Asahi Kasei gains royalty income from Prevymis, a cytomegalovirus drug whose global rights Aicuris had licensed to Merck. The Japanese company also gets an experimental antisense oligonucleotide that Aicuris has advanced to Phase 1 testing as a treatment for BK virus infection in kidney transplant patients.

    Photo by Asahi Kasei

  • TRrexBio’s IPO Bags $116M to Bring the Immune System Back Into Balance

    TRrexBio’s IPO Bags $116M to Bring the Immune System Back Into Balance

    Immunology research continues to draw investment for new ways to suppress excessive immune responses. TRexBio takes a different approach, tapping into the body’s built-in way of keeping the immune system in balance. A TRex-discovered molecule is progressing in the clinic in the hands of partner Eli Lilly. Now the biotech has $116.7 million in IPO cash to support clinical development of its wholly owned assets.

    Late Thursday, TRex priced 8.33 million shares at $14 each, which was the low end of the preliminary price range it had set earlier in the week. Those shares began trading on the Nasdaq Friday under the stock symbol “TRXB.”

    The research of South San Francisco-based TRex focuses on regulatory T cells, or Tregs. While the activity of immune cells leads to inflammation, the body counterbalances that with Tregs, which tamp down excessive immune responses and stop the immune system from attacking healthy tissue.

    There are some biotech companies developing Treg cell therapies made by harvesting and engineering a patient’s own Tregs or working with Tregs sourced from healthy donors. While there’s evidence that these approaches can work, the commercialization of T cell therapies for cancer shows the logistical hurdles of engineering cells into living medicines. There’s one FDA-approved Treg so far, a blood cancer treatment developed by Orca Bio. It’s made by shipping a sample of patient blood to an Orca facility that isolates Tregs. Those cells are then shipped back for infusion into the patient. The complexity, cost, and time for manufacturing Treg cell therapies likely limits its use in large autoimmune disease populations, TRex said in its IPO filing.

    Rather than working with directly with Tregs, TRex aims to leverage Tregs already in the patient’s body. Its drugs are fusion proteins designed to activate and expand Tregs that are in inflamed tissue as a way of restoring immune balance. The company says its drugs can do so selectively, without also activating proinflammatory immune cells. These drugs come from a TRex platform technology that gleans immunology insights by analyzing a database of healthy and diseased tissue samples.

    “Our approach is designed to address disease at its source — in the tissue — by developing medicines focused on tissue immune homeostasis that we believe have the potential to provide a durable clinical benefit,” TRex said in the filing.

    TRex formed in 2018. In 2021, Lilly participated in the biotech’s Series A financing. Two years later, the pharma company paid $55 million up front to begin a research collaboration. The alliance produced TRB-051, which is designed to modulate immune effector cells. In June, TRex said Lilly plans to advance TRB-051 to Phase 2a testing in lupus with cutaneous involvement.

    TRex’s most advanced wholly owned program is TRB-061, which is designed to activate tumor necrosis factor receptor 2 (TNFR2), expanding and activating Tregs in inflamed tissues. In August, TRex reported Phase 1a results showing activation and expansion of Tregs in the tissue of healthy volunteers. The study drug was also well tolerated and no serious adverse events were reported. The results supported dose selection for a Phase 1b test in patients with moderate-to-severe atopic dermatitis; preliminary data are expected in mid-2027. TRex also describes alopecia areata as a “priority indication,” pointing to published studies supporting the role of Tregs in mediating the hair follicle cycle and hair regrowth.

    A second TRex drug candidate, TRB-071, is designed to activate the protein CD30 to augment tissue Tregs and block immune system inflammatory signaling. In the filing, TRex points to genetic studies supporting the involvement of CD30 and its ligand in inflammatory bowel disease. The company plans to start a Phase 1 test in the first half of next year.

    In its history as a private company, TRex said it had raised about $220 million. Lilly paid TRex a $15 million milestone payment in 2024 and the biotech is eligible to receive up to $577.5 million more in additional milestone payments, according to the filing. TRex last raised money early this year, a $50 million financing.

    A 2021 collaboration agreement with a Johnson & Johnson affiliate was terminated last year, according to the filing. But the document also shows Johnson & Johnson Innovation—JJDC owns a 4.6% post-IPO stake. Lilly is TRex’s largest shareholder with a 16.8% stake after the IPO, followed by the 14.1% owned by SV Health Investors. TRex said Lilly has expressed an interest in purchasing additional shares at the IPO price in an amount not to exceed 19.9% of the company, but there is no binding commitment for the stock purchase.

    As of the end of the second quarter of this year, TRex reported its cash position was $90.9 million. Combined with the IPO proceeds, TRex plans to spend about $90 million to bring TRB-016 through the readout of topline Phase 2 data in atopic dermatitis and alopecia areata and $10 million for the start and completion of TRB-071’s Phase 1 test in healthy volunteers. The company estimates its capital will last into the second half of 2029.

    Retension Pharma Reels In $45M for Next-Gen Hypertension Drug

    Retension Pharmaceuticals joined the public markets with an IPO that raised $45 million for a drug in clinical development for uncontrolled hypertension.

    Retension’s RTN-001 is a small molecule inhibitor of an enzyme called PDE-5. In its IPO filing, the company notes that first-generation PDE-5 inhibitors, such as the sexual dysfunction drug Viagra, were initially studied in cardiovascular indications such as hypertension and angina. Retension contends these drugs did not offer adequate bioavailability and tissue penetration to address cardiac tissue, leading to their failure as blood pressure medications.

    Falls Church, Virginia-based Retension describes RTN-001 as a next-generation PDE-5 inhibitor engineered for better bioavailability and increased distribution to places such as the aorta and its branches. In two Phase 2 pilot trials, the company said the once-daily pill led to clinically meaningful placebo-adjusted reductions in blood pressure.

    “We believe RTN-001 has the potential to be an effective treatment for hypertension with a favorable safety profile and thus be part of an anti-hypertensive treatment approach,” Retension said in its IPO filing.

    The molecule that is now RTN-001 was originally developed by a company called Surface Logix. It has changed hands several times; in 2023, Retension licensed all rights to the molecule from Redux Therapeutics. As of the end of June, Retension reported its cash position was about $13.5 million. That capital along with the IPO proceeds will go toward clinical development of RTN-001, Retension’s only drug candidate.

    The company plans to spend about $18 million to complete an ongoing Phase 2b test of RTN-001 in uncontrolled hypertension. Preliminary data are expected in the first half of 2027. Another $10 million is budgeted for preparing for a planned Phase 3 test in this indication.

    Retension offered 3.75 million shares priced at $12 each, which was the midpoint of the price range the biotech set in preliminary financial terms earlier in the week. Those shares began trading on the Nasdaq Friday under the stock symbol “RTSN.”

    Public domain image by Flickr user NIH Image Gallery

  • STAT+: Life Biosciences share glaucoma study updates for its cellular reprogramming drug

    STAT+: Life Biosciences share glaucoma study updates for its cellular reprogramming drug

    NIH funding uncertainty thwarts U.S. researchers, Argenx stumbles, and more biotech news

    Close up of an eye
    Adobe

    Jason is a general assignment reporter, with particular focus on genetic medicine and rare disease. Confidential tips can be sent on Signal at JasonMast.77.

    Want to stay on top of the science and politics driving biotech today? Sign up to get our biotech newsletter in your inbox.

    This is the Readout. Please read it.

    And don’t miss us too much Monday, when the newsletter will be paused for the holiday. We’ll be back in your inbox Tuesday.

    STAT+ Exclusive Story

    Already have an account? Log in

    STAT+

    STAT+

    This article is exclusive to STAT+ subscribers

    Unlock this article — plus in-depth analysis, newsletters, premium events, and news alerts.

    Already have an account? Log in

    View All Plans

    To read the rest of this story subscribe to STAT+.

    Subscribe

    1. Meghana Keshavan covers biotech and contributes to The Readout newsletter.

    2. General Assignment Reporter

      Jason is a general assignment reporter, with particular focus on genetic medicine and rare disease. Confidential tips can be sent on Signal at JasonMast.77.